
US Credit Cards With an ITIN
Yes. A non-US resident can hold real US credit cards on an ITIN, with no Social Security Number anywhere in the process.
The three nationwide bureaus can compile a file on an ITIN together with your name, your US addresses, and your date of birth. Every card that reports to that file builds it.
What decides the outcome is not the number. It is the first approval, because an empty file gives an issuer nothing to price.
First Class Citizen's method is built around that single obstacle. The first card is opened in person, on a Miami visit they organize, and it is usually in hand within three to seven business days.
The engagement is advisory. They open the door and hand you the sequence. Every account stays in your name.
Why the ITIN is enough, and what actually blocks you
A Social Security Number is not a requirement for a US credit file. Without one, Experian can compile your credit history from other identification elements: your name, your addresses for the past two years, and your date of birth.
An ITIN sits in that set as the taxpayer number a non-US citizen holds. Accounts reported by lenders attach to the file exactly as they would for anyone else.
So the number is not the wall. The wall is the emptiness behind it.
An issuer underwrites risk from history, and a brand-new ITIN file carries none. No repayment record, no US address depth, no prior relationship.
Add a remote applicant with a foreign passport and a foreign phone, and a routine online application gives the bank every reason to decline. That first yes is the entire problem, and it is worth solving deliberately.
The number is rarely the blocker. The first approval is, and that one is solvable.
Book Your Assessment CallWhich credit cards accept an ITIN
One of them publishes it plainly. In Chase's own credit-card education library, read on 31 July 2026: if you already have a Social Security Number or an Individual Taxpayer Identification Number, you should be able to apply for most credit cards.
Their application checklist says the same thing in list form. The identifier it asks for is a Social Security number or an Individual Taxpayer Identification Number.
So the ITIN is not a workaround. At one of the largest issuers in the country it is the number the application is designed to take.
What no issuer publishes is whether your application will be approved. Chase draws that line itself in the next sentence: credit history, income and other factors are used to evaluate the application.
So acceptance is not a policy you can look up. It is settled at the application, and an issuer underwrites the file rather than the number.
Which makes a list of card names the wrong thing to go looking for.
The same number in front of the same bank is not the same application twice, because what moves is the history behind it, the address depth, and whether anyone is sitting across the desk.
What can be shown is where cards have actually opened. On this method that has been Bank of America, Wells Fargo, Chase, Capital One, and Citibank, in person, with the documents in hand.
What can also be shown is what each bank puts in writing. Below is each one in its own words, with the date the page was read and what the sentence does and does not commit them to.
Citi
Citi, about its own secured card. This is what applying asks for, never what approval grants.
You can apply for the Citi® Secured Mastercard® easily online or at Citi branches. You’ll need to provide some personal identifying information to apply, including your name, address and SSN or ITIN.
This article is for educational purposes. It is not intended to provide legal, investment, or financial advice and is not a substitute for professional advice. It does not indicate the availability of any Citi product or service.
Everything published about Citi and an ITIN
U.S. Bank
U.S. Bank, about its own secured card. Its help pages and its published online application flow are both below.
No. We can only upgrade your secured credit card if you have an SSN. If you have an ITIN, you can continue to have a secured account and use your card.
Enter your SSN. We will use this to confirm you're not subject to backup withholding with the IRS.
Spend within your limit and pay your bill when it's due. Over time, this will help build your credit and you may be able to graduate to a traditional card.
Everything published about U.S. Bank and an ITIN
American Express
American Express, about its own Card application. Applying, never approval.
Passport details, U.S.-issued Social Security Number (SSN), or U.S.-issued Individual Tax Identification Number (ITIN)
Wells Fargo
Wells Fargo, about its deposit accounts. Not about its credit cards.
Know your Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN)
If you're under 18 or a non-permanent U.S. resident, you’ll need to make an appointment to apply in person at a Wells Fargo branch.
Discover
Discover, about the market. Not about Discover.
Social Security number or Individual Taxpayer Identification Number (if the card issuer accepts it)
What best means when nobody publishes a ranking
Every list promising the best cards for ITIN holders is ranking something nobody has published. Approval is decided inside the application, so no honest league table exists.
What can be ranked is what has opened. In the published record the first cards come from Bank of America, Chase, Capital One, Wells Fargo and Citibank, several of them against a deposit.
The premium names people actually want, a Sapphire or a Platinum, appear later in the same record. They follow months of reported activity rather than arriving at the start.
So best is not a card. It is the card your file can open now, and the one after it that the first one makes possible.
How the first card actually gets opened
First Class Citizen clears that first approval in person. The card is opened on a Miami visit they organize, one to two days on the ground.
Which banks work with an ITIN applicant?
The banks they work with for ITIN applicants are Bank of America, Wells Fargo, Chase, Capital One, and Citibank. Sitting in a branch with your documents, your ITIN, and an introduction changes what the bank is looking at.
The card is usually in hand within three to seven business days.
One line on the model
One line on the model, because it decides what you are buying. They advise, they organize the visit, and they hand you the sequence.
They do not touch your accounts, and they cannot. Every card, every login, and every statement stays yours.
The prerequisite is the number itself
The prerequisite is the number itself. If you do not hold an ITIN yet, that step comes first, covered end to end in the complete ITIN guide, and having the application handled for you is one way to take it. A US bank account belongs in the same opening move.
Which bank, which product, which order. Thirty minutes settles all three.
Book Your Assessment CallWhat the file does in the months that follow
From the first approval it becomes a reporting game, and the clock is set by the bureaus rather than by anyone selling a service. You typically need three to six months of reported activity before a score exists at all.
Inside that window, the levers are ordinary
Inside that window the levers are ordinary, and they are the whole job. Pay on time every time. Keep the balance low against the limit.
Resist applying for several cards at once, because a burst of applications reads to lenders as financial strain.
On First Class Citizen's method, clients reach a 720 score in about four to six months. That is the number worth planning around, and it is what opens the next tier: Chase Sapphire and American Express Platinum.
What that tier is good for
What that tier is good for is covered in from a first card to travel points, and the timeline itself in how fast a US score can really be built.
If you run a US LLC, the LLC owner's guide covers how the two files interact.
Cards that landed on an ITIN file
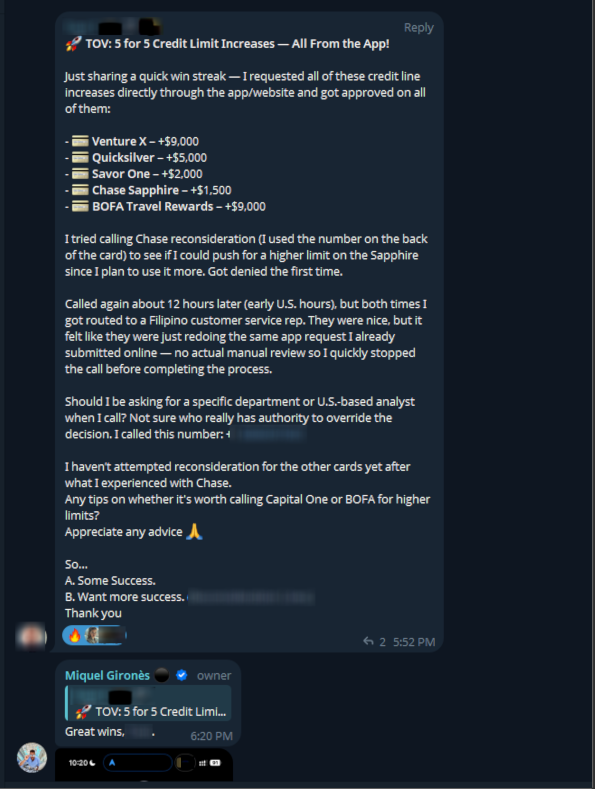
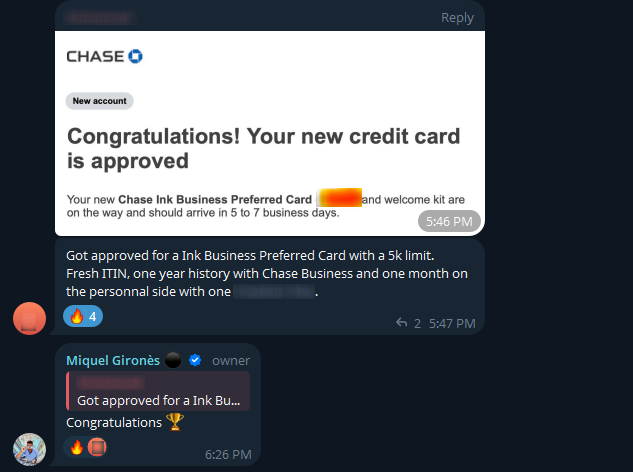


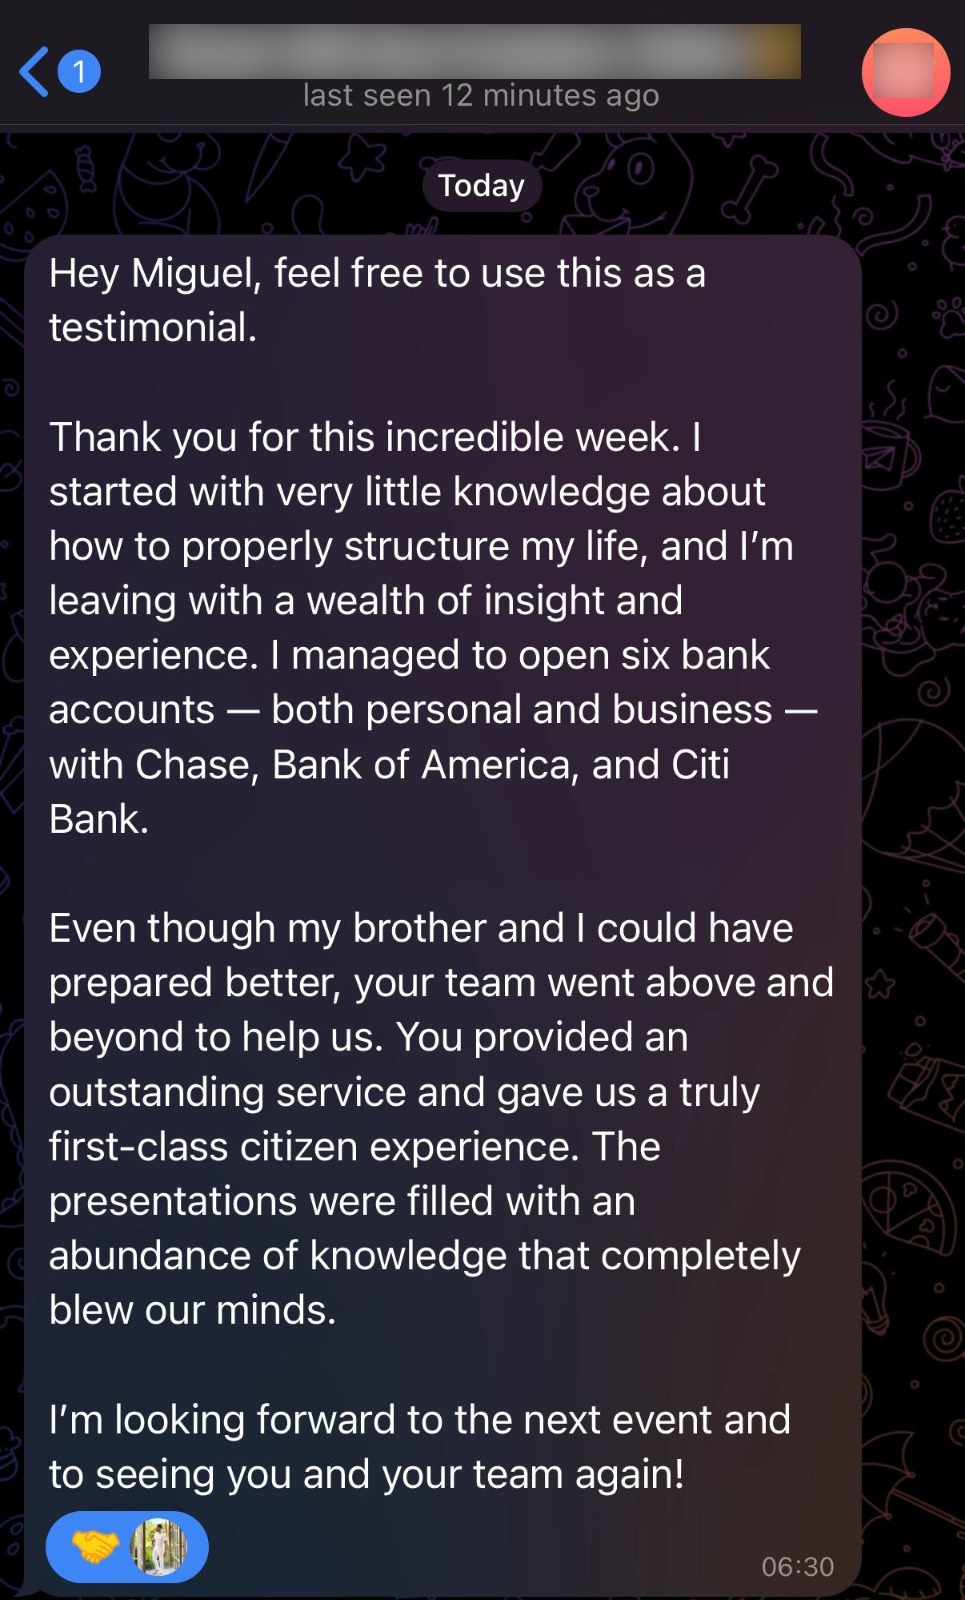
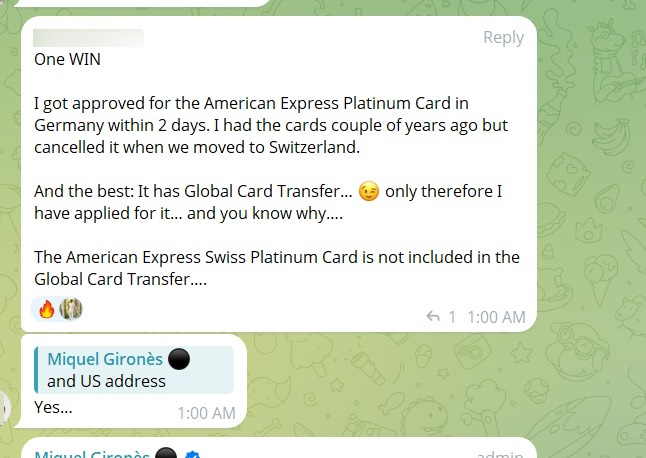
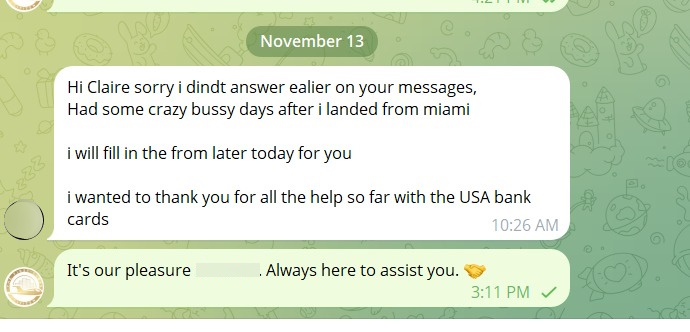
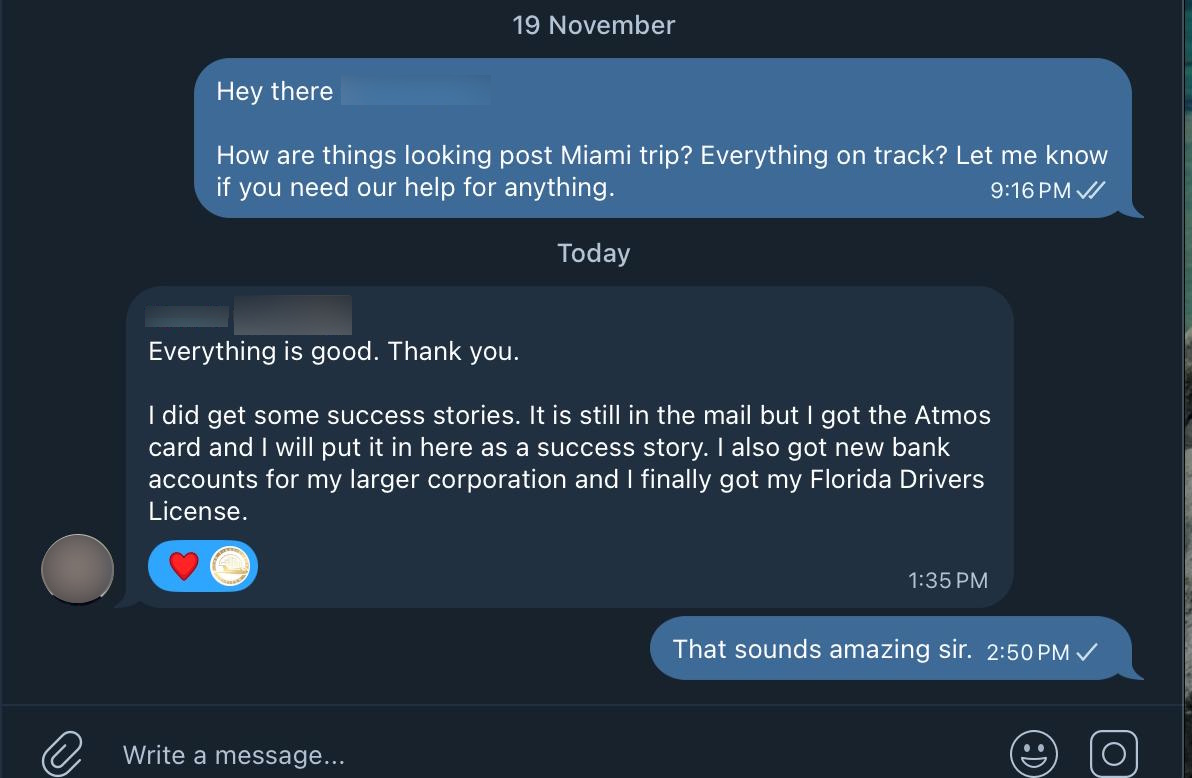

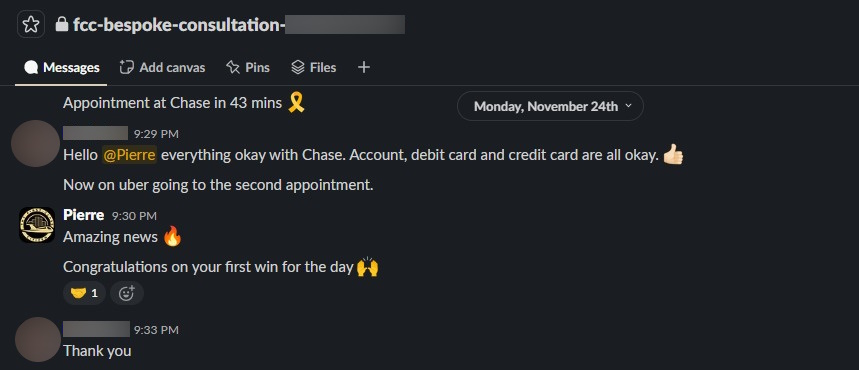
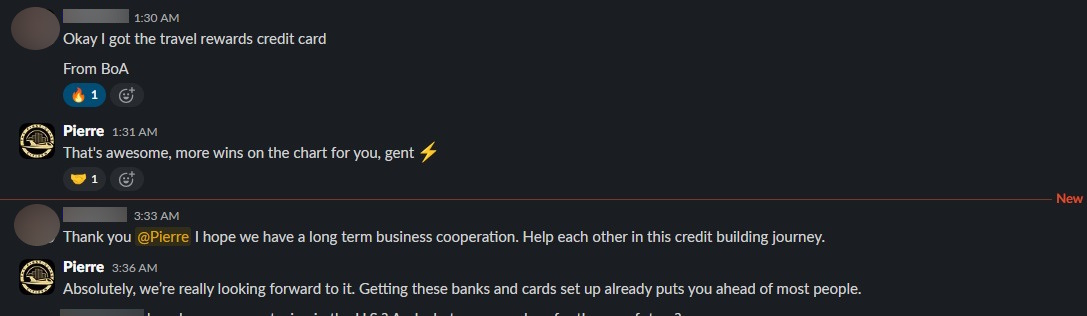
Real client wins, straight from the Hall of Wins.
The US credit series
- Find your routeTell it what you are trying to do and it maps the guides to read in order.
- ITIN document checklistPick your situation, get the exact list the IRS accepts.
- What it costsPublished prices and timelines, service by service.
- US credit calculatorWhat your spend returns at the rates issuers publish today.
FAQ
Which credit cards accept an ITIN?
What are the best credit cards for ITIN holders?
Do banks accept an ITIN for credit cards?
Can I apply for a credit card with an ITIN number?
Can I get a US credit card as a non-citizen?
Can I get a US credit card without an SSN?
Which banks work with an ITIN applicant?
How long until the card is in my hand?
Do they apply for the cards for me?
Do I need an ITIN before any of this?
When can I apply for a premium card like a Sapphire or a Platinum?
Will applying to several banks at once speed it up?
Sources
The published pages this guide draws on, each read on the date shown.
- citi.com read 2026-08-02
- usbank.com read 2026-08-05
- usbank.com read 2026-08-05
- usbank.com read 2026-08-05
- americanexpress.com read 2026-08-02
- wellsfargo.com read 2026-08-02
- wellsfargo.com read 2026-08-02
- discover.com read 2026-08-02
Get the first approval right
The assessment call maps your route from an ITIN to a first card to a real score, and it is direct about what the Miami visit involves and what it does not. Free, qualified, and straight to the point.
Book Your Assessment CallThis guide reports what the authorities and institutions involved publish, quoted, with the date each source was read. It is not tax, legal or immigration advice. Published rules change, and an individual case can turn on facts no page can see.

Founder & CEO, The First Class Citizen